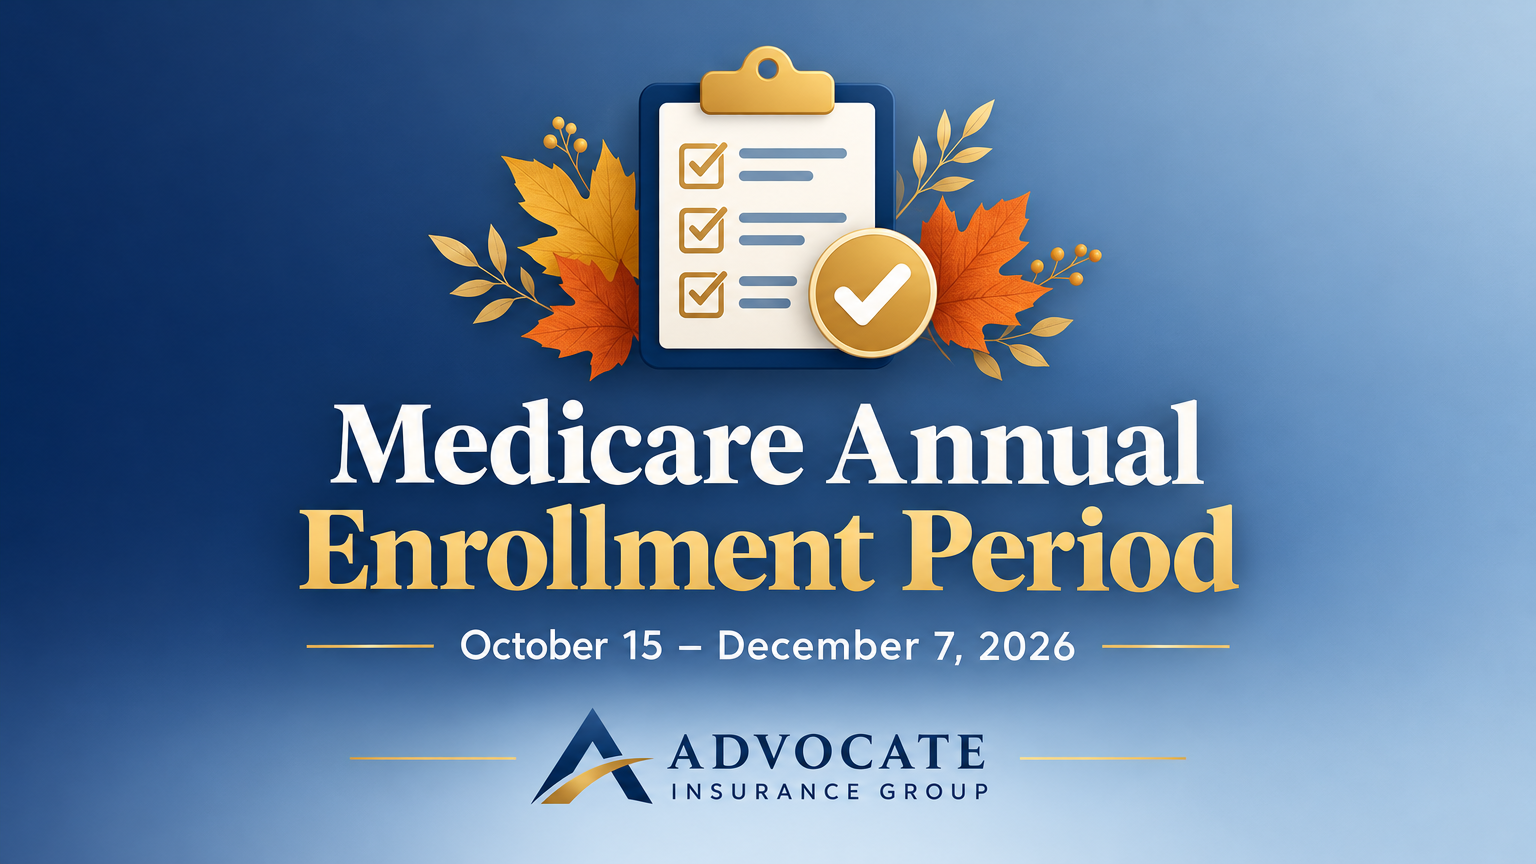
The Medicare Annual Enrollment Period runs October 15–December 7, 2026. Here's what to review, what's changing, and how to make sure your 2027 coverage fits your life.
This post is for anyone in the Greenville, SC area — and across the Upstate — who is already on Medicare and wants to make sure their plan still fits going into 2027. The Medicare Annual Enrollment Period (AEP) opened on October 15, 2026, and runs through December 7, 2026. Any changes you make take effect January 1, 2027. You don't have to make a change — but you do owe it to yourself to take a look.
Quick Answer: The Medicare AEP runs October 15 – December 7, 2026. During this window, anyone on Medicare can switch, drop, or add a Medicare Advantage (Part C) or Part D prescription drug plan. Coverage changes begin January 1, 2027. This window does not apply to Original Medicare (Parts A and B) or Medigap policies, but it is a smart time to review all of your coverage.
Why This Enrollment Window Matters
Every fall, Medicare plans can change. Premiums, deductibles, drug formularies, provider networks, and extra benefits like dental or vision coverage may all shift from one year to the next. Your plan sends you an Annual Notice of Change (ANOC) in late September — that letter tells you exactly what is different for 2027.
If you haven't read yours yet, dig it out. If you tossed it, don't worry — a free review with a licensed local agent can walk you through the same information and help you compare your options side by side, at no cost to you.
The AEP is also your annual opportunity to ask: Does my current coverage still fit my life? Your health situation, your prescriptions, and your doctors may have changed. Your plan should keep up.
What You Can Do During AEP (October 15 – December 7, 2026)
Here is what the Annual Enrollment Period allows you to do, regardless of which type of Medicare coverage you currently carry:
- Switch from one Medicare Advantage plan to a different Medicare Advantage plan
- Switch from Medicare Advantage back to Original Medicare (Parts A and B)
- Switch from Original Medicare to a Medicare Advantage plan
- Add, switch, or drop a Part D prescription drug plan
- Drop Medicare Advantage and add a stand-alone Part D drug plan
What AEP does not cover: Medigap (Medicare Supplement) policies have their own enrollment rules and are not part of the AEP window. If you are thinking about adding or changing a Medigap policy, ask your agent about the right timing for your situation.
Your AEP Review Checklist
Use this checklist as a starting point for your annual review. Go through it yourself, or bring it to a free conversation with a licensed agent who can fill in the gaps.
1. Pull Out Your Annual Notice of Change
Your current plan mailed this to you by September 30. It lists every change for 2027: premiums, deductibles, copays, covered drugs, and network providers. Read the summary pages first, then dig into the details that affect you most.
2. Review Your Prescription Drug List
Check whether every medication you take is still on your plan's formulary for 2027. Look at the tier level too — a drug can stay on the formulary but move to a higher (more expensive) tier. If any of your prescriptions shifted, it may be worth comparing Part D plans or Medicare Advantage options that include drug coverage.
For 2027, the finalized Part D maximum deductible is $700, and the Part D out-of-pocket cap is $2,400 (finalized). These numbers matter when comparing plans that carry a deductible against those that do not.
3. Confirm Your Doctors Are Still In-Network
Networks change every year. If you are on a Medicare Advantage plan, verify that your primary care doctor, any specialists you see regularly, and your preferred hospital are still in-network for 2027. A plan that looked great last year could become less convenient if key providers dropped out of its network.
4. Check Extra Benefits You Actually Use
Many Medicare Advantage plans offer dental, vision, hearing, and other supplemental benefits. Review what your current plan offers and whether you are actually using those benefits. Some plans offer options in these areas that may be a better fit for your situation — but benefits vary by plan and area, so a side-by-side comparison matters.
5. Consider Whether Original Medicare + Medigap Is a Better Fit
Medicare Advantage and Original Medicare with a Medigap policy work very differently. Advantage plans often have lower or no premiums but use networks and require prior authorizations. Original Medicare gives you nationwide access to any provider who accepts Medicare, and a Medigap policy helps cover the costs Original Medicare does not pay. Neither option is right for everyone — the right choice depends on your health, budget, travel habits, and preferred doctors.
6. Ask About the Medicare Savings Program
If your income is below a certain level, your state may help pay your Part B premium through the Medicare Savings Program. This program is underutilized — many people who qualify simply do not know it exists. At Advocate Insurance Group, we help clients complete this application at no charge. As we like to say: the worst they can say is no.
7. Look at Extra Help for Drug Costs
Extra Help (also called the Low-Income Subsidy, or LIS) reduces Part D costs — including premiums, deductibles, and copays — for people who qualify based on income and resources. If your financial situation has changed since you last checked, it may be worth applying or reapplying this year.
What Changes in Medicare for 2027?
The 2026 Part B standard premium is $202.90 per month (official). The 2026 Part B deductible is $283 per year. The 2026 Part A deductible is $1,736 per benefit period.
For 2027, the Medicare Trustees Report projected the Part B premium at approximately $209.50 per month and the Part B deductible at approximately $292 — but these are projected figures only, not yet official. CMS typically announces final 2027 numbers in November 2026. We will update our resources as soon as the official figures are released.
What is finalized for 2027: the Part D out-of-pocket cap is $2,400, the Part D maximum deductible is $700, and the Part D base beneficiary premium is $41.33 per month.
Common Questions About AEP
Q: Do I have to do anything during AEP if I'm happy with my current plan?
A: No, you are not required to make any changes. If you do nothing, your current plan automatically renews for 2027. However, it is still worth reviewing your ANOC to make sure the plan's terms have not changed in a way that affects your care or costs.
Q: Can I switch from Medicare Advantage to Original Medicare during AEP?
A: Yes. AEP is one of the windows when you can return to Original Medicare (Parts A and B). Keep in mind that if you want to add a Medigap policy, there may be medical underwriting involved depending on when you first enrolled and your state's rules. Ask a licensed agent to walk through your specific situation.
Q: What if I miss the December 7 deadline?
A: If you miss AEP, you may still have options. There is a Medicare Advantage Open Enrollment Period from January 1 through March 31, during which you can make one switch if you are already enrolled in a Medicare Advantage plan. You may also qualify for a Special Enrollment Period if you experience certain life changes. An agent can help you figure out what options apply to you.
Q: Is it really free to get help from an insurance agent during AEP?
A: Yes. Independent insurance agents like Antinea Martin at Advocate Insurance Group are compensated by the carriers — not by you. There is no charge for a consultation, a plan review, or enrollment help.
Q: I use the VA for my healthcare. Do I need to worry about AEP?
A: VA care and Medicare work together, and enrolling in Medicare Parts A and B can give you access to local doctors and hospitals outside the VA system — useful for second opinions, urgent care, or if a VA facility is not close by. If you have not yet enrolled in Medicare, your eligibility rules are separate from AEP. If you are already enrolled in Medicare alongside your VA care, AEP rules apply to any Advantage or Part D plans you carry. Talk to a licensed agent who understands both programs.
You Don't Have to Navigate This Alone
The AEP window is 54 days — enough time to review your options thoughtfully, without pressure. At Advocate Insurance Group in Greenville, SC, Antinea Martin helps Medicare members across the Upstate review their current plans, compare available options, and make informed decisions. Her guidance is always free, and she takes time to explain things in plain language.
Whether you are staying put, switching plans, or simply want someone to confirm that your current coverage still makes sense, a free review is a good use of your time this fall.
Have questions about your enrollment options?
We'll walk you through every step — at no cost to you.